Market Intelligence
Understanding the Numbers: AHRI Shipment Report Breakdown for April 2024
July 18, 2024 | 3 minute read

The latest AHRI shipment report offers a bit of positive news: the annual pace of unitary shipments has stopped falling for all three product lines (ACs, ASHPs, and furnaces):
Air conditioner shipments bottomed at 5 million.
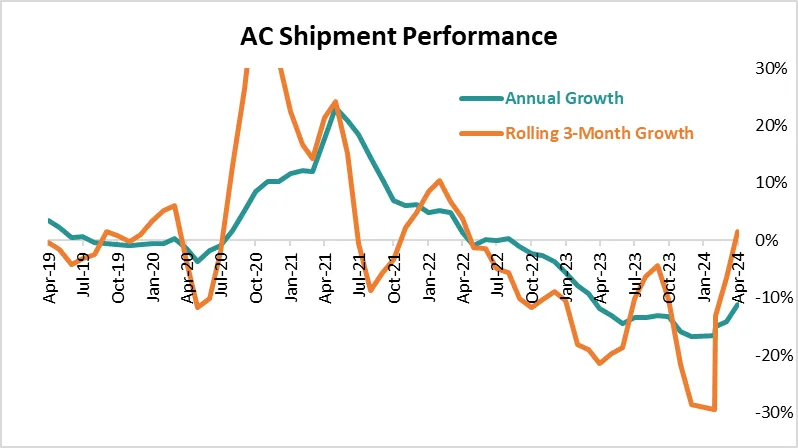
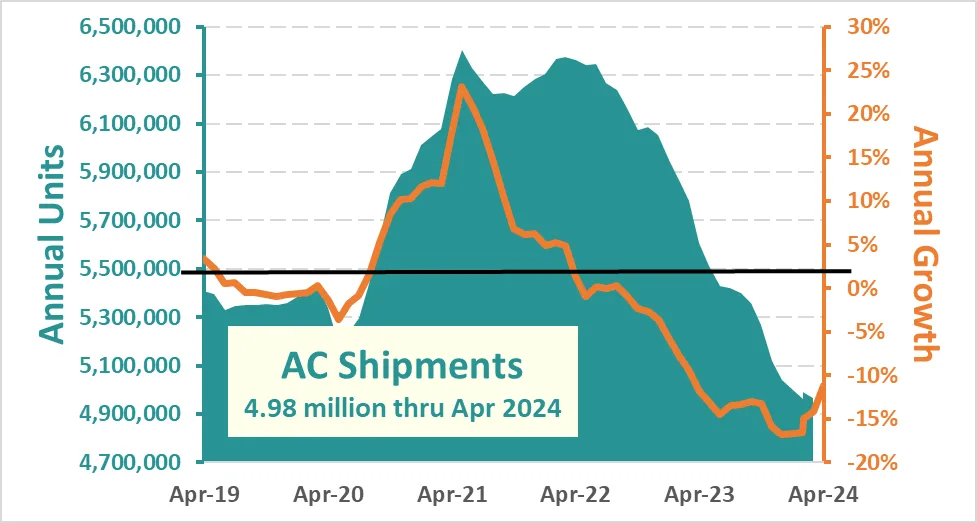
There were 434.2K air conditioners shipped during April 2024, a decline of 3.6% from April the previous year. The 3-year average for AC shipments decreased by 19.3%. The total number of AC shipments over the past 12 months amounts to 4.98 million, which is down 11.2% from one year ago. Year-to-date AC shipments show a decline of 3.8%. January through April typically represents 30% of annualized shipments, which currently implies a rate of 5.09 million or an increase of 2.2% from the last 12 months.
Annual pace of heat pump shipments have found a base at 3.6 million.
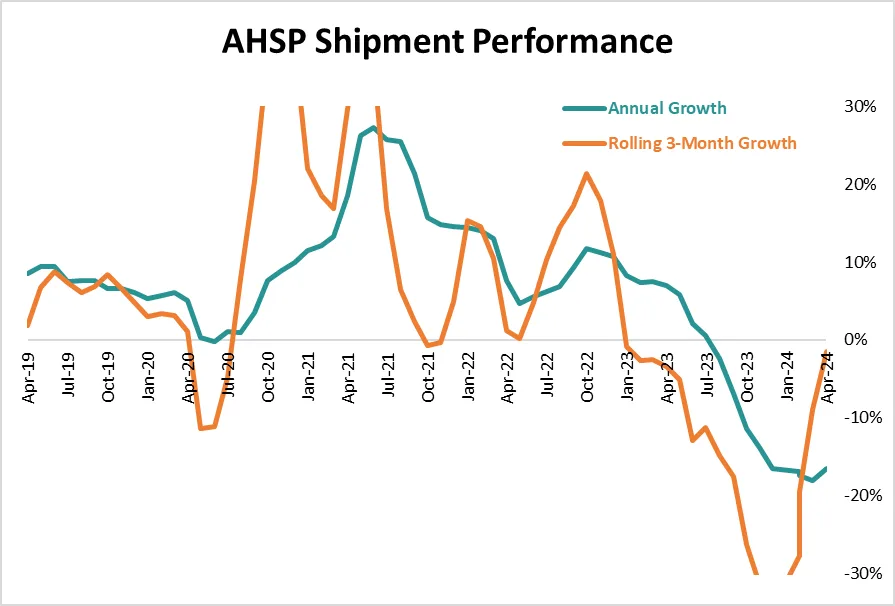
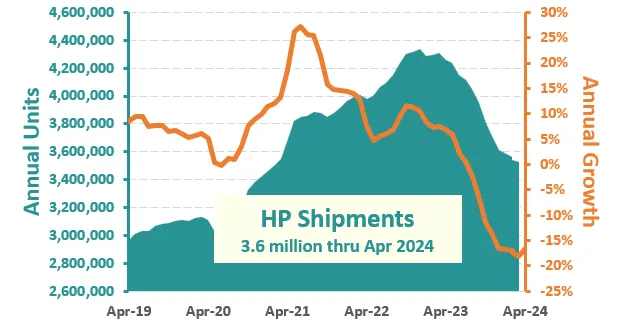
There were 314.4K Heat Pumps shipped during April 2024, an improvement of 7.3% from April 2023. The 3-year average for heat pump shipments decreased by 7.7%. The total number of heat pump shipments over the past 12 months amounts to 3.55 million, which is down 16.5% from the 12 months through April 2023. Year-to-date heat pump shipments show a decline of 5.1%. January through April typically represents 33.3% of annualized shipments, which currently implies a rate of 3.6 million or an increase of only 1.4% from the last 12 months.
Furnace shipments found a floor at 2.9-million-unit annual rate.
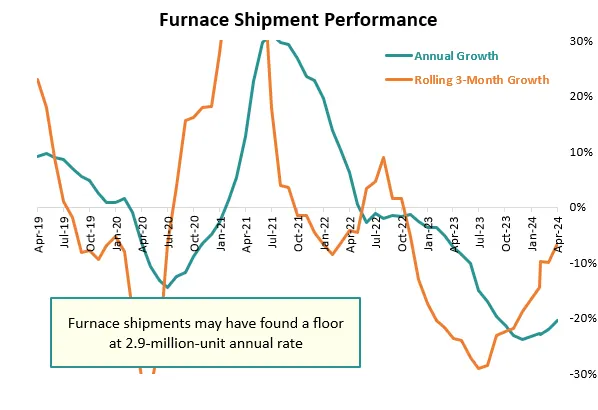
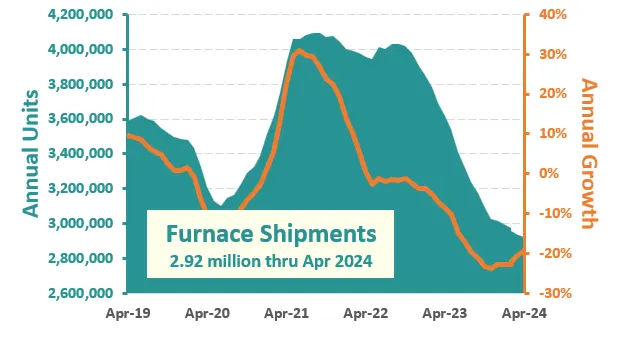
During April 2024, there were 236.3K furnace shipments (a combination of natural gas and oil), a decline of 5.7% from April the previous year. April 2024 furnace shipments were 22.8% lower than the recent 3-year average for shipments for April. Over the last year, furnace shipments totaled 2.92 million, down by 19.2% from April 2023. Year-to-date furnace shipments have declined by 8.8% through April 2024. January through April typically represents 27.9% of annualized shipments, which currently implies a rate of 3.27 million or an increase of 12% from the last 12 months.
Over the past four years, HARDI distributors have experienced a wide range of sales performance. At the onset of COVID-19, the annual pace (in dollars) for distributor sales was just a tick under 4%. Two years later, that figure had climbed to 25%. Now, another two years on, and the annual rate has fallen back to near-zero percent growth. This return to zero is driven by normalizing demand patterns, and the same pattern is visible in manufacturer shipment data from AHRI. Historically, the median annual sales growth has been around 6%, with price increases averaging about 2.5%. HARDI expects distributor sales growth to improve through the remainder of 2024 and resume a more historically typical growth pattern in 2025.
Learn More About Unitary Product Movement
While sales performance figures from our monthly Trends Report and AHRI shipment data offer a window into unitary market performance for distributors, they can’t compete with the real thing. HARDI’s new and improved Unitary Market Report offers essential insights to help you understand your market position and identify areas of growth or loss. Contact Tim Fisher or Grace Helser to learn how to get involved.
Grace Helser
Senior Research Analyst
As a Senior Research Analyst on HARDI's Market Intelligence team, Grace leverages her education in business and economics from the Ohio State University to provide industry insights and benchmarking programs for HARDI membership. She has a strong foundation in analysis and statistical methods, which she utilizes through in-depth survey work to develop comprehensive membership insights.