Market Intelligence
Summer Hours: An Outlook on Contractor Demand
September 7, 2023 | 2 minute read
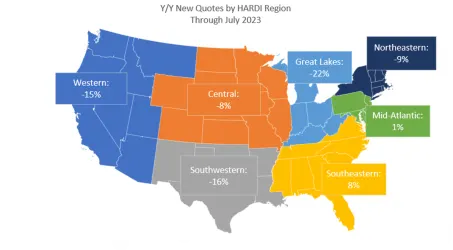
Source: Field Edge New Quotes
Field Edge is a platform used primarily by HVAC contractors to manage customers and services. They provide HARDI data averaging new quotes and new invoices across their user base as well as the average quote/invoice $ amount. “New Quotes” is a relatively good proxy for replacement demand as quotes will typically involve replacement or installation of a new system whereas “New Invoices” captures more repair work. These estimates are not perfect, though, as some users have reported including non-HVAC related work in their reporting.
New Quotes
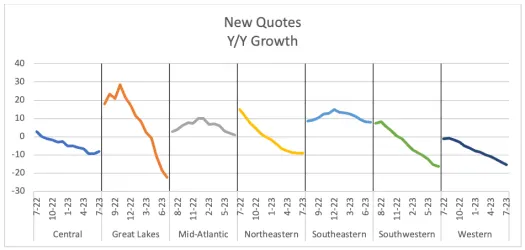
Through the summer, new quotes provided by contractors in the Great Lakes have improved a lot since April but remain deep in the red. Northeast, West, and Southwest states are inching closer to neutral growth with August showing some potential for further recovery. The Central and Mid-Atlantic regions have stayed roughly the same since March. The Southeast was the only positively growing region through Q1, and the annual growth nearly doubled through Q2.
Average Quote Value
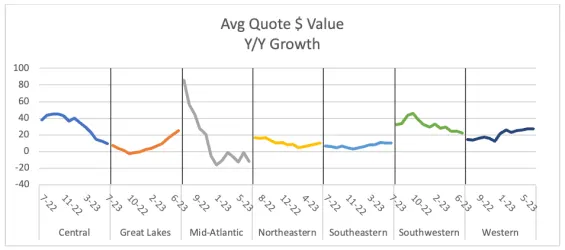
While overall quotes seem to be normalizing, many regions are experiencing growth in the $ value of quotes and invoices which will protect both contractor and distributor margins. Except for the Mid-Atlantic states, which have exhibited high variance in the last few years, the amount quoted to end users lies around the 10% growth range with some regions pushing 20-30% growth.
Growth in the Central region quote values declined nearly 30 percentage points in Q2, falling from 38% to 9%. When considered alongside stagnant growth in new quotes provided, it appears safe to conclude that replacement demand opportunities in the Central region are drying up. Quote totals in the Great Lakes grew to 24% alongside an improvement in the number of new jobs. Quote values in the Northeast and Southeastern regions remain around the 10% level that was present in Q1, and the Southeast also exhibits positive job growth. Finally, growth in Southwestern and Western quote values remain in the mid-to-high 20%’s.
Overall, the trends in New and Replacement end user demand is not as strong as the unsustainable growth during the pandemic era, but slowly we are getting back to normal. Weak weather this year as well as the expectation of a stronger economic end to 2024 sets distributors and contractors up for a stronger summer next year.

Tyler Drown
Former Quantitative Research Analyst at HARDI
Tyler previously served as an analyst on the Market Intelligence team, where he used his background in economics and statistics to deliver content on market insights that helped members make informed, data-driven decisions.