Market Intelligence
Quick Hits: A Market Intelligence Update
July 29, 2022 | 3 minute read
GDP Declines for Second Consecutive Quarter:
GDP declined at an annual rate of 0.9 percent in the second quarter. In the first quarter, real (inflation-adjusted) GDP declined 1.6 percent.
The decline in GDP reflects changes in the seasonally adjusted annual rate relative to the preceding quarter and is not a year over year calculation. If it were, it would show that economic activity as measured by GDP increased 1.6 percent from Q2 2021.
The decrease in real GDP reflects decreases in areas relevant to HARDI members, specifically investments in inventory and construction (both residential and nonresidential).
Is this a Recession? It’s Complicated:
Consumer spending increased in Q2 by a 1 percent annual rate, even after accounting for inflation. However, the annual rate declined from 1.8 percent in Q1.
At 3.6 percent, the unemployment rate is nearly as low as it was on the eve of the Covid-19 outbreak. The employment-to-population ratio declined slightly in June to 59.9 percent (down from 60.1 percent in May) but remains 1.9 percentage points higher than one year ago.
There were 11,245 job openings in May, which is 16 percent higher than one year ago. However, the seasonally adjusted number of openings has steadily declined the past two months after peaking in March.
Demand for HVAC/R Products Remains High, but a Slowdown is Evident:
Through June, the dollar-weighted 12-month moving sales total for HARDI distributors was up 22.5 percent from last year. For the month itself, HARDI distributors saw a 17.2 percent jump in sales from June 2021.
The producer price index for air-conditioning, refrigeration, and forced air heating equipment was up 20.8 percent in June, indicating that distributors experienced negative real growth for the month.
New orders to HVAC/R manufacturers were down 8 percent through May, while unfilled orders were up 11 percent (down from a high of 20 percent in January). Industrial production for HVAC/R manufacturers declined for the second straight month in June and is down 17 percent from last year.
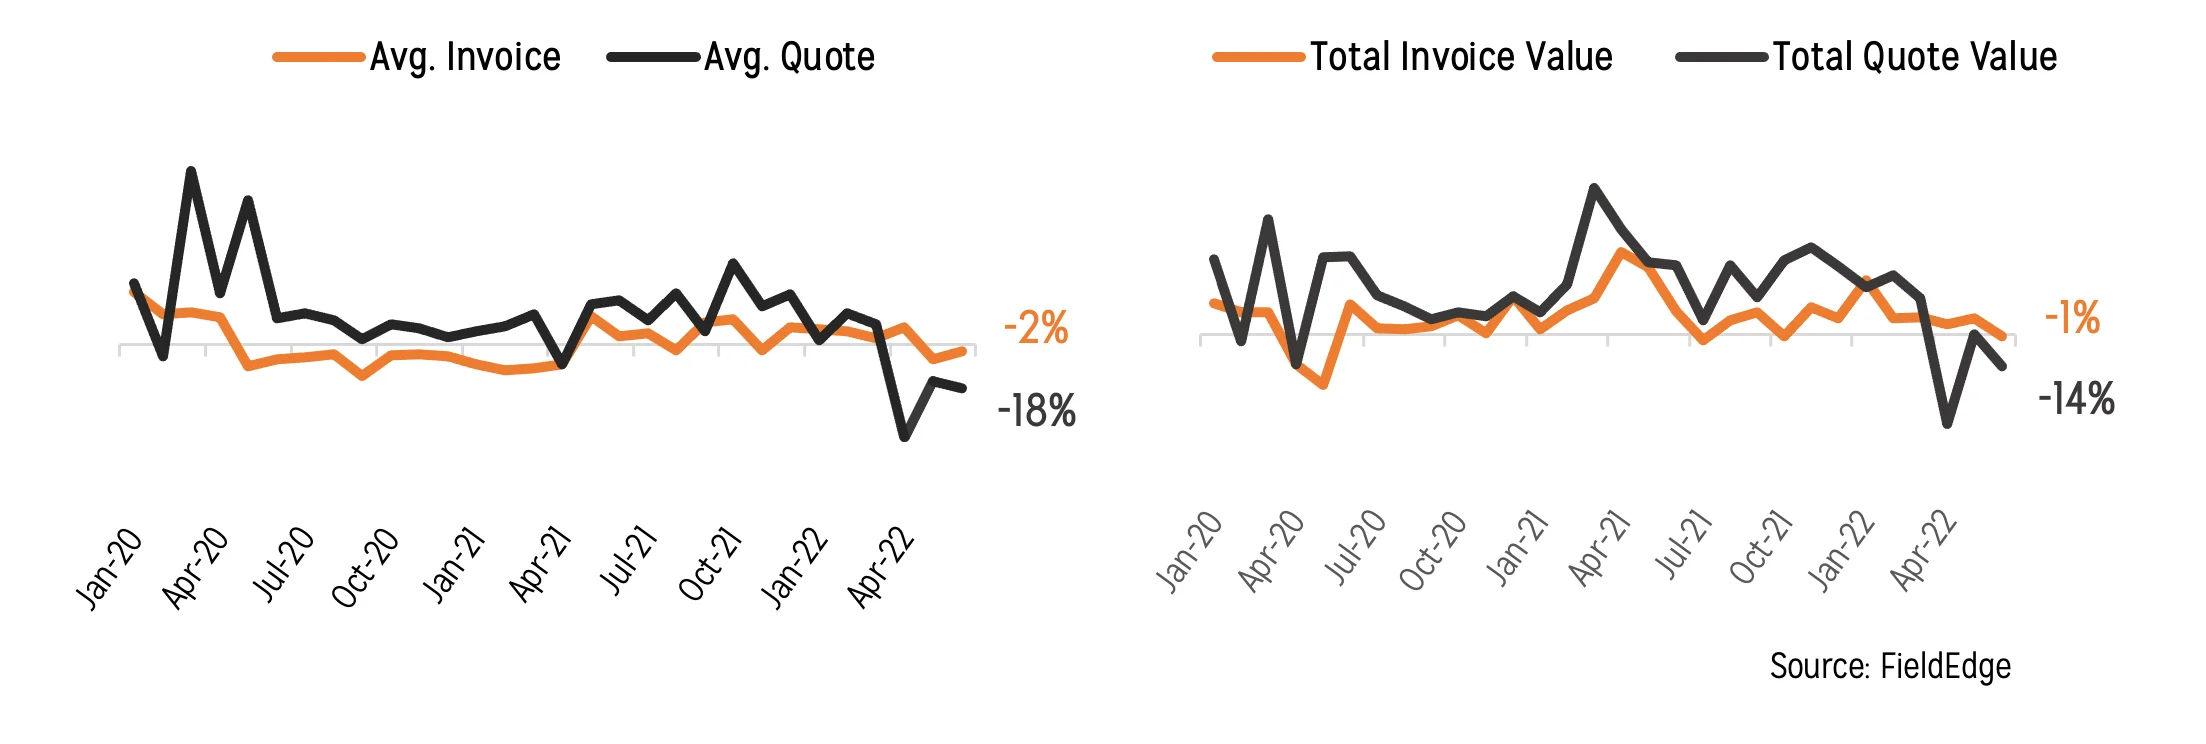
Data from FieldEdge shows that the average invoice and quote sizes declined in June, with the average invoice size from contractors declining by 2 percent and the average quote size declining by 18 percent from one year ago. Similarly, the total value of invoices and quotes issued also declined in June, with invoice values down 1 percent and quote values down 14 percent from one year ago.
Things are much less uniform on a regional level, with several HARDI regions seeing growth in real demand through June. To learn more about the regional variations and hear what the Market Intelligence team expects for the rest of the year, be sure to register for our joint webinar with FieldEdge on August 3rd. You can register for the webinar here.
Tags:

Tim Fisher
Vice President of Research & Knowledge Management
Tim leads research and analysis of HVACR market trends, with a focus on wholesale distribution. His work is widely cited, and he was named an ACHR News Top 40 Under 40 professional in 2021. Before HARDI, he directed Government and External Affairs at CDFA, working on federal policy. He holds degrees from Ohio University (B.A., M.A.) and Ohio State (MBA).