Market Intelligence
New Census Data Highlights Trends in Data Center Demand
September 24, 2024 | 3 minute read

When it comes to analyzing HVAC/R market data, insight into the specifics of the commercial space is often difficult. Often our best estimates of new construction and investment in existing properties in the nonresidential space comes in the form of the Value of Construction Put-in-Place (PIP) series from the Census. This series sums the dollar value of all materials, labor, and overhead spent on construction projects within a month including installation of HVAC units. To measure the Nonresidential space, we typically look at the Lodging, Hospitality, Commercial, Healthcare, Manufacturing, and Office space subcategories to inform our analyses. Over the past year, growth rates in office spending in particular have grown at rates contrary to what other market factors would suggest. Starting in May, however, this is no longer a mystery as the Census Bureau has begun separating out Data Center as another subcategory in office space.
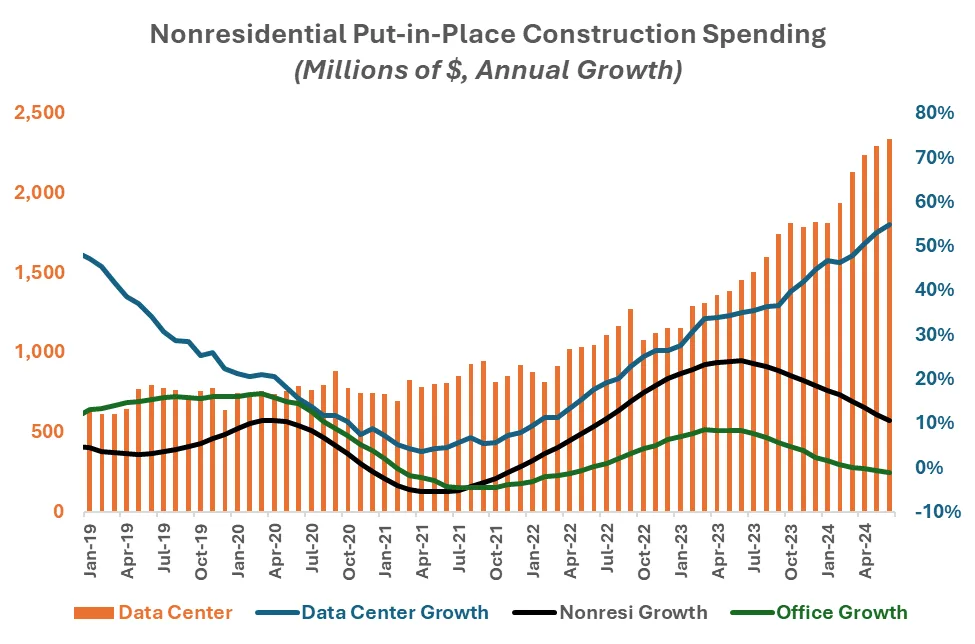
The chart above shows the total spend on Data Centers PIP construction contrasted with the growth rate of total nonresidential spend and the whole of the office subcategory. This shows a stark contrast to the trend of total nonresidential and office space growth over the last few years. Total nonresidential has recovered from the pandemic to a healthy 11% growth through June. Total office space saw a bit of recovery through the middle of 2023 but has since gone flat to negative growth. Data Centers, however, have continued to climb at a rapid rate especially over the second half of 2023 into 2024 with 53% annual growth through June. If you were to subtract data center spend from the total office subcategory, the annual growth rate in June drops from a modest -1% to almost -13%.
This trend highlights a key dynamic distributors operating in the commercial space should be aware of. Office space has been on the decline since the pandemic fueled by high interest rates and increased remote work. What used to be a staple of commercial HVAC demand is expected to remain weak through 2024, but data centers offer a large tailwind for the HVAC industry.
Explore More HARDI Benchmarking
HARDI's Market Intelligence team offers a diverse set of reporting that allow members to measure their company against key financial and performance metrics, track sales trends by equipment and geography, evaluate Supply Chain performance, and even assist in employee SG&A management.
Learn more and explore what HARDI's Market Intelligence team is providing members.

Tyler Drown
Former Quantitative Research Analyst at HARDI
Tyler previously served as an analyst on the Market Intelligence team, where he used his background in economics and statistics to deliver content on market insights that helped members make informed, data-driven decisions.