Market Intelligence
Managing Costs and Inventories: Adapting to a Lengthening Cash Conversion Cycle
July 26, 2023 | 3 minute read

High inventory levels have pushed the cash conversion cycle for distributors to historic levels.
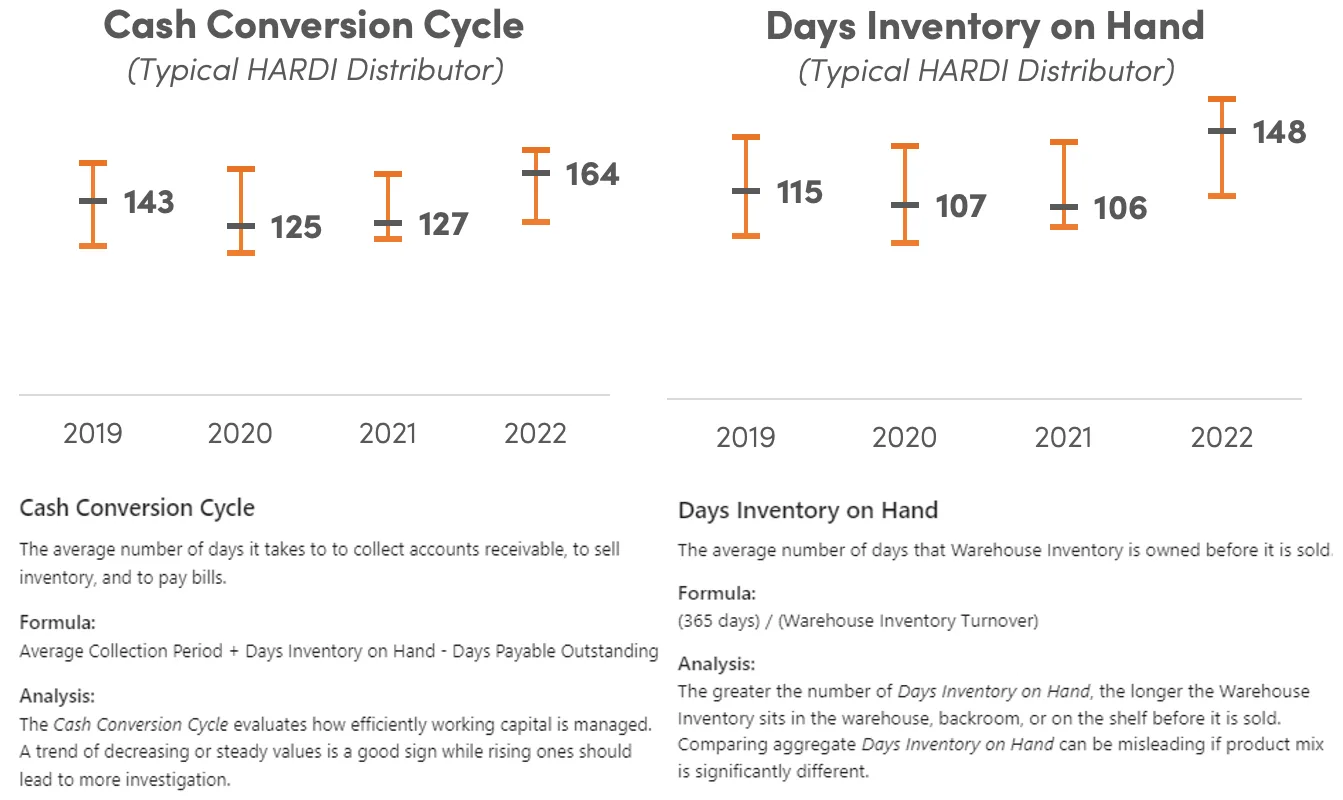
If a picture is worth a thousand words, then the 2 charts above must certainly convey an essay’s worth of detail. The charts, built with data taken from our Annual Benchmarking Survey (ABS), clearly show just how out of whack things became for HARDI distributors last year, and the challenging position many find themselves in midway through 2023.
Cash Conversion Cycle:
Average Collection Period + Days Inventory on Hand – Days Payable Outstanding
Prior to 2022, the cash conversion cycle for the typical HARDI distributor had only moved north of 150 days twice: in 2015 (154 days) and 2017 (153 days). In 2022, however, the cash conversion cycle for the typical HARDI distributor leapt to 164 days: 37 days above 2021 totals and 20 days above its pre-Covid average of 144. Unsurprisingly, the growth in distributor inventory totals explains most of the 2022 increase in the cash conversion cycle.
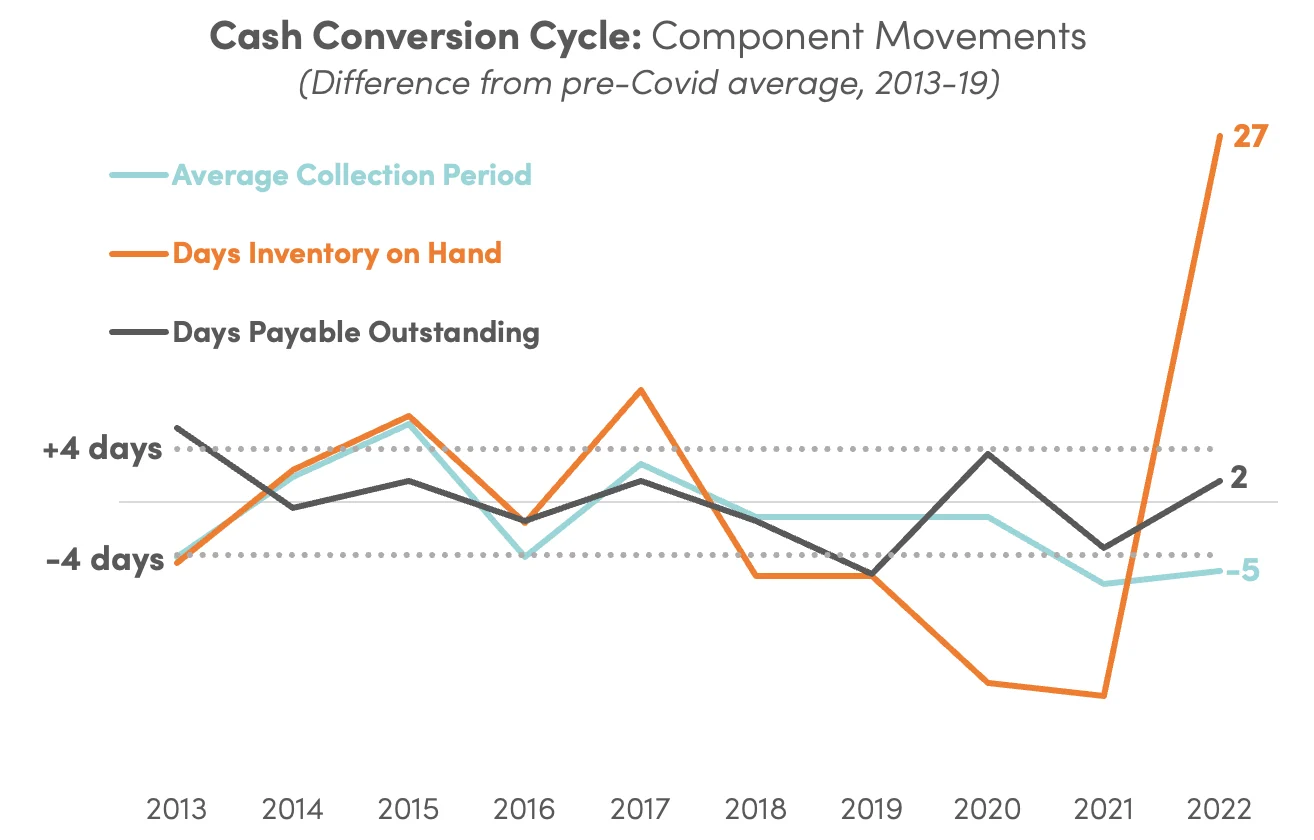
The chart above, which shows the difference (in days) between the typical distributor’s annual cash conversion cycle metrics and the pre-Covid average, illustrates the outsized impact that changes in distributor inventory totals have had on cash conversion totals in recent years. During the pre-Covid years for which we have benchmarking data, the 3 metrics that constitute the cash conversion cycle total have generally fallen within a range of ± 4 days. Since 2020, days inventory on hand totals have visibly swung well outside the ± 4-day range – impacting the near-term liquidity of HARDI distributors. Less visible has been the decline in average collection periods (aka days sales outstanding), which has helped to subsidize the massive growth in distributor inventories. Unfortunately, on a month-to-month basis the average collection period – reported as days sales outstanding in our monthly Trends report – has begun a slow and steady creep upward, while annual sales totals continue to edge lower.
For distributors to ensure a profitable 2023 in the face of slowing demand, they must attack expense management in the same way they tackled record demand amid supply chain disruptions in ’20, ’21, and ’22. Knowing how your expenses – whether in personnel or operations – compares to your peers is critical for making smart choices, and for that reason we encourage distributors that haven’t yet submitted their Annual Benchmarking Survey to do so immediately. Participation is free to all HARDI distributors, and this year participants also gain access to a fascinating webinar from Dan Craddock and Barry Swaney of Catalyst on how best to manage inventories in the months ahead.
Interested in participating?
Contact Tim Fisher for more details.

Tim Fisher
Vice President of Research & Knowledge Management
Tim leads research and analysis of HVACR market trends, with a focus on wholesale distribution. His work is widely cited, and he was named an ACHR News Top 40 Under 40 professional in 2021. Before HARDI, he directed Government and External Affairs at CDFA, working on federal policy. He holds degrees from Ohio University (B.A., M.A.) and Ohio State (MBA).